All Categories
Featured
Comparing LTC Coverage Versus Medicare
Table of Contents
Hybrid policies can protect both income and estate. Consist of real-life care situations: dementia, movement loss, single-spouse requirement. In-home vs. facility, family participation, care quality. Medicare is essentialbut it's inadequate on its own. The best time to plan for long-term care is when you do not require it. Because the assurance you'll have later on starts with the decisions you make today.
serves as the Chief Financial Investment Officer at Langan Financial Group. In this function, he handles financial investment portfolios, serves as a fiduciary for group retirement plans, and talks to customers regarding their financial goals, threat tolerance, and asset allotment. With a focus on ERISA Law, Alex graduated orgasm laude from Widener Commonwealth Law School.
Alex is also enthusiastic about giving back to the community, and has actually gotten involved in The Foundation of Enhancing Neighborhoods' Emerging Philanthropist Program, volunteers at his church, and works as a board member of Samara: The Center of Person & Household Growth. Outside of work and offering, Alex enjoys his time with his better half Sarah, and their three kids, Rory, Patrick, and Ava.
Why to Fund Critical Illness Insurance
Your business. Your family's future. Each deserves thoughtful planning that begins with what matters to you. Langan Financial Group offers monetary planning and investment management for individuals, households, and entrepreneur. With workplaces in Camp Hill and York, Pennsylvania, we serve clients throughout Central Pennsylvania. We assist you work through concerns about retirement earnings, financial investment decisions, Social Security, and how taxes might impact your monetary strategy.
From there, we assist you assess your alternatives and develop a plan that can evolve as your life modifications. We also help businesses and organizations examine workplace retirement strategies and comprehend their obligations as strategy sponsors. The content is established from sources thought to be supplying precise information. The information in this material is not planned as tax or legal suggestions.
The opinions expressed and material offered are for basic info, and need to not be considered a solicitation for the purchase or sale of any security.
Most Americans wrongly believe Medicare will cover their long-lasting care requirements in retirement. This critical misunderstanding can lead to ravaging financial consequences when care is eventually needed.
Comparing Long-Term Care Coverage Versus Medicare
The relationship between long-term care (LTC) and healthcare covered by TRICARE, Medicare, or employer health care can be confusing. Examples of health insurance coverage include your health insurance at work, TRICARE or TRICARE for Life, and Medicare. These cover medical costs associated with the treatment of a sickness or injury.
After treatment, recuperation or recovery is not covered. It's about the requirement for support when you can't perform typical activities of life and you need help to function.
Numerous individuals believe of LTC as nursing home care. A better description would be stay-at-home care.
Growth Strategies With Life Insurance Policies
A lot of Americans wrongly think Medicare will cover their long-lasting care requirements in retirement. This important misunderstanding can lead to ravaging financial consequences when care is eventually needed. Medicare offers limited protection for long-term care services: Up to 100 days maximum Requires a certifying 3-day healthcare facility stay first Days 21-100 need a daily copayment ($200+ per day in 2025) Should show constant improvement to maintain protection Restricted coverage Requires physician certification of medical requirement Need to be competent nursing care (not custodial) Care need to be part-time or intermittent only the support with activities of day-to-day living that Medicare does not cover:.
While it may be hard to think about now, it's most likely that you'll need some kind of health care or everyday living assistance as you age. Individuals often believe that Medicare covers long-term care, either in your home or in a nursing facility, however sadly, that's not the case. Medicare does not cover assisted living, competent nursing, or long-term care.
If you're not able to leave your house for medical or therapeutic care, Medicare will pay for home health care services. It can include a variety of advantages for people who need consistent medical attention and/or custodial care with day-to-day activities like consuming, bathing, or mobility in facilities from helped living to full-time, in- home custodial care to a private room in a nursing facility.
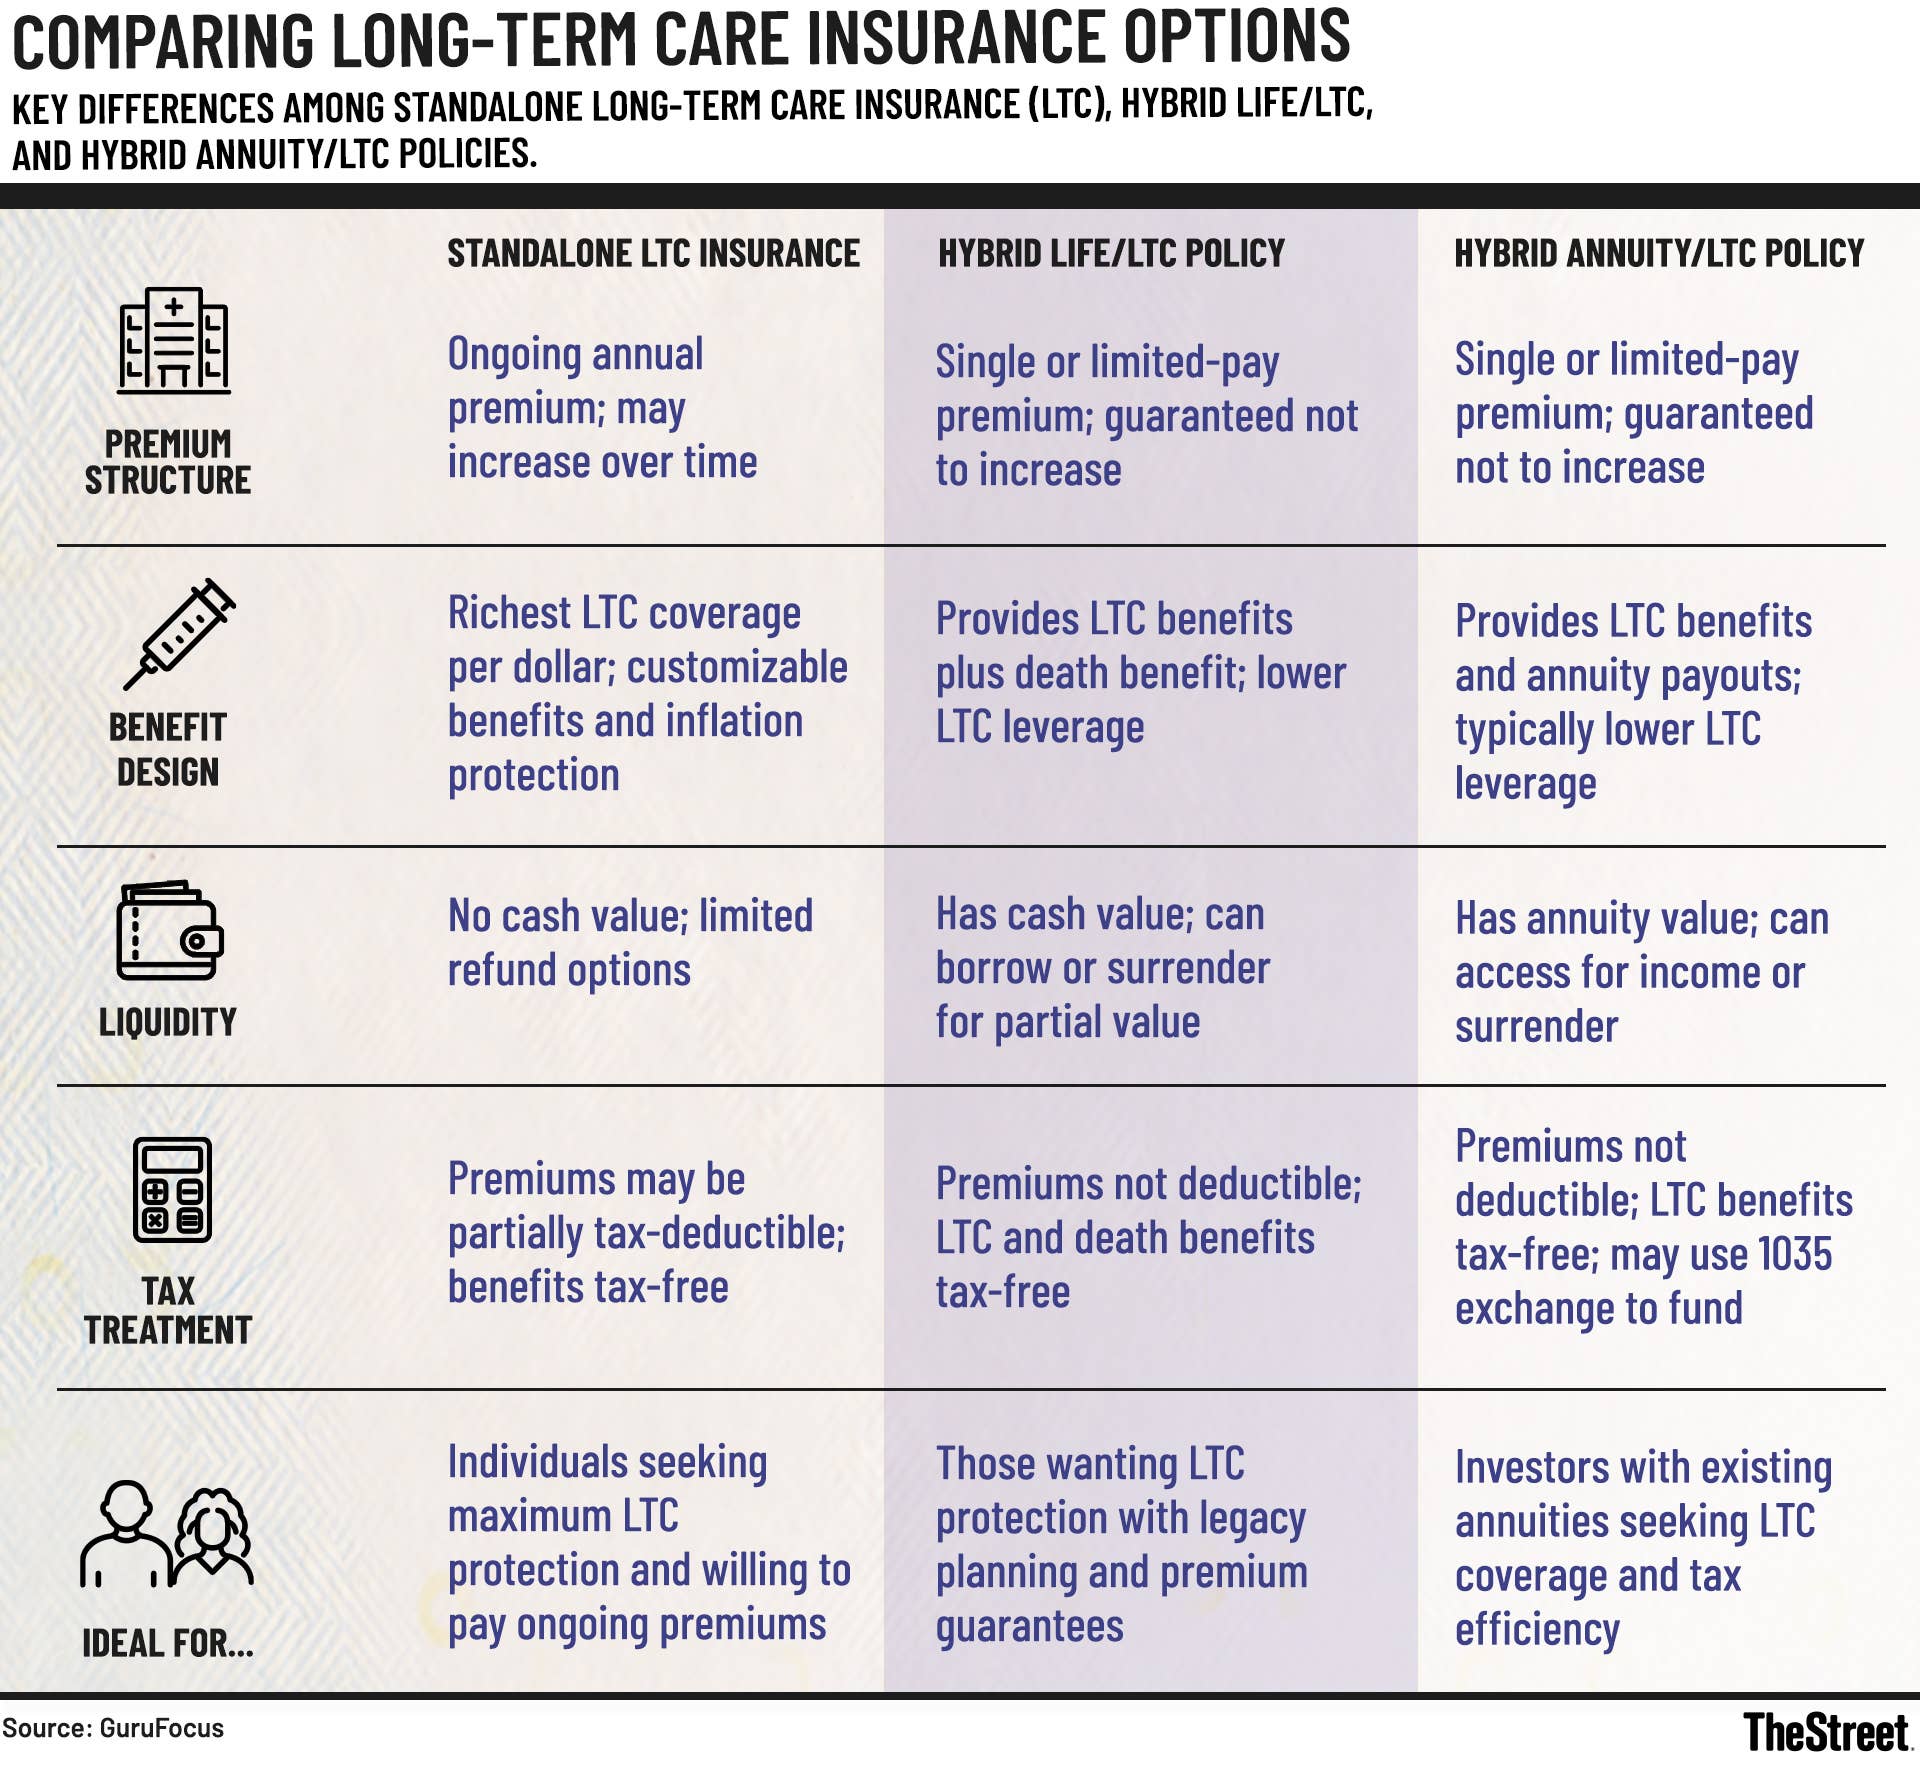
The expense of a long-lasting care policy is based upon age, preferred advantage amount and any additional advantages you pick to consist of. That's why it is very important to determine your long-term care needs and level of security before it becomes an emergency situation. Considering long-term care is a cornerstone in any monetary plan, and there are lots of options to pick from based upon your monetary circumstance and needs.
Retirement Planning Santa Ana CAVariable and Fixed Annuities for Seniors
It's better to be overprepared and covered, than underprepared and financially ravaged.
Medicare does not cover your long-lasting nursing care or 24/7 at home services, nor does it spend for your custodial care which includes your daily activities such as consuming, bathing, and dressing.

Why do lots of monetary consultants tell customers they can self-insure for long-lasting care but encourage them to purchase supplemental coverage to Medicare? This question has afflicted me for 30 years. The primary factor this subject is so essential is that the most typical objection my group and I experience regarding long-lasting care insurance coverage is, "I'm going to self-insure." Lots of people really prefer the defense of insurance coverage, yet their financial advisor often recommends that self-insurance is preferable.
They consistently purchase Part D drug protection, either matched with Medicare Advantage or a conventional Medicare supplement. Financial consultants seldom advise against purchasing additional Medicare coverage.
Using Life Insurance for Retirement Income
The typical claim payment is substantially less than $4,000 per year, according to Telos Actuarial. For 2026, there is a $2,100 cap on drug coverage under Part D. If you do not believe me that the claim payments are little, take a look at the Description of Benefits that shows the claim payments from your Medicare Supplement or Part D drug strategy.

Latest Posts
Securing Your Savings With Accident Coverage

Estimating Future LTC Costs

Comparing Long-Term Care Coverage Versus Medicare