All Categories
Featured
Unified Senior Strategies for 2026
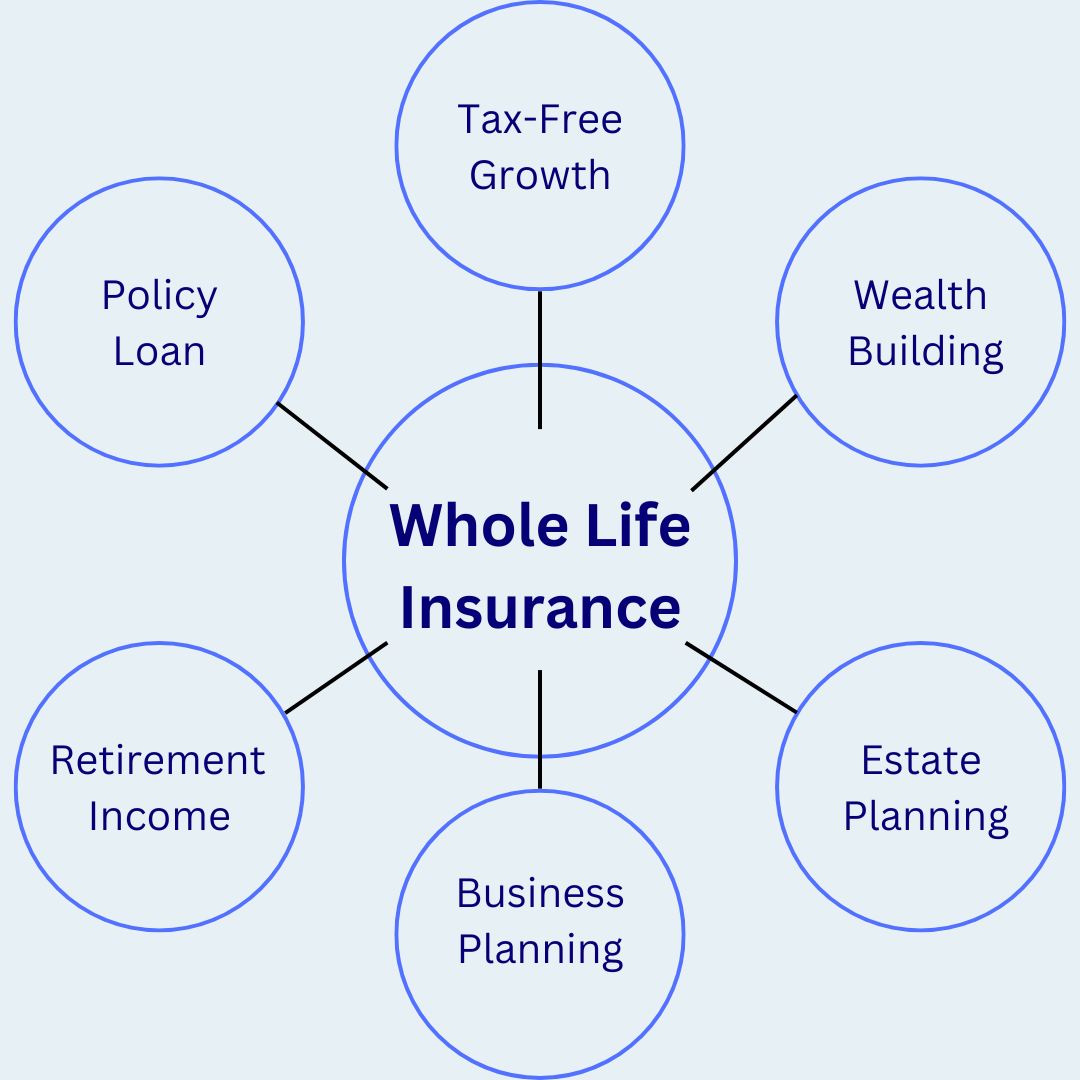
Regularly review and adjust both your retirement savings and life insurance protection to line up with altering life scenarios and monetary goals. Understanding the distinctions between retirement strategies and life insurance coverage is essential for effective financial planning. By incorporating both into your monetary strategy, you can secure a comfortable retirement for yourself and provide comfort for your family's future. Click here or the photo below to set up an in-person, virtual, or phone call meeting. We look forward to working with you!. By Carl Lachman, CFP, MBAIt is possible to put a great deal of money into part of a particular type of life insurance coverage policy, let the cash grow tax-free for years, then take the money out tax-free when you retire. No income tax. No capital gains tax. This sounds like the perfect strategy to pay for your retirement.
It is not a way to identify who the excellent guys and bad guys are, but rather simply a method to determine who has satisfied the minimum requirements for being able to offer insurance coverage. Insurance representatives are certified to offer and get a commission for their sales. If they sell an insurance coverage policy, they get.
paid. A better way to get advice is to consider an authorized financial investment consultant. These specialists (like me)typically provide extensive financial planning advice and handle your financial investments. They are legally required to follow the fiduciary standard, putting your interests before their own interests. And, they are not paid by commissionexceeds the tax basis will be subject to tax);(3)withdrawals taken during the first 15 goes beyond years do not cause, occur at the time of, or during the two years prior very first, any reduction in benefitsTrigger and Happen4)the policy does not throughout a modified endowment contract. Any policy withdrawals, loans, and loan interest will minimize policy worths and may minimize advantages. Life Insurance coverage: Death benefits are generally tax-free for beneficiaries; some policies provide tax-deferred money value development.
Regularly review and adjust both your retirement cost savings and life insurance coverage to line up with altering life situations and monetary goals. Comprehending the distinctions in between retirement plans and life insurance coverage is important for reliable financial planning. By Carl Lachman, CFP, MBAIt is possible to put a lot of cash into part of a specific type of life insurance coverage policy, let the money grow tax-free for years, then take the cash out tax-free when you retire.
It is not a way to identify who the excellent guys and bad guys are, however rather simply a way to identify who has met the minimum requirements for having the ability to offer insurance coverage. Insurance representatives are certified to offer and get a commission for their sales. If they sell an insurance coverage, they get.
When Seniors Require Critical Illness Policies
paid. A better way to get suggestions is to consider an authorized investment consultant. These experts (like me)generally provide detailed financial preparation guidance and handle your investments. They are lawfully required to follow the fiduciary requirement, putting your interests before their own interests. And, they are not paid by commission, but a lot of are instead "fee-only,"which indicates they charge their customers an annual charge and don't make money in any other way. In the case of this insurance/retirement tactic, you pay thousands and thousands of dollars above the premium. This money develops in the policy far above the annual expense of the policy.
Retirement Planning San BernardinoRegularly review and adjust both your retirement cost savings and life insurance coverage to line up with altering life circumstances and monetary objectives. Understanding the differences between retirement plans and life insurance is crucial for effective financial preparation. By integrating both into your monetary method, you can secure a comfy retirement on your own and provide assurance for your family's future. Click on this link or the picture below to set up an in-person, virtual, or call conference. We anticipate dealing with you!. By Carl Lachman, CFP, MBAIt is possible to put a great deal of money into part of a specific type of life insurance policy, let the cash grow tax-free for many years, then take the money out tax-free when you retire. No income tax. No capital gains tax. This seems like the ideal plan to spend for your retirement.
It is not a way to identify who the good guys and bad guys are, but rather simply a method to determine who has actually satisfied the minimum requirements for being able to offer insurance coverage. If they offer an insurance policy, they getpaid. This cash builds up in the policy far above the annual cost of the policy.

Latest Posts
Addressing the Cost Burden of Longevity in 2026

Strategic Financial Planning for Longevity in 2026
Managing Aging and Long-Term Care Costs in 2026