All Categories
Featured

Why Seniors Can Use Accident Insurance
Table of Contents
In addition to the service provider, long-term care insurance costs depend upon elements consisting of health, age, marital status, gender, and policy type. A lot of long-lasting care insurance plan need a medical examination. If you are in great health, then your premium likely will be lower. If you have a household history of chronic health conditions, then you will likely have a greater premium since it indicates to an insurer that there's a greater chance you'll require long-lasting care.
If you acquire a policy when you're older, then you are most likely to require the advantage to spend for care quicker, so premiums will be greater. Studies reveal that married or partnered individuals have a lower risk of requiring long-term care, so married individuals will have lower premiums. Couples can also bundle their policies together for a lower rate.
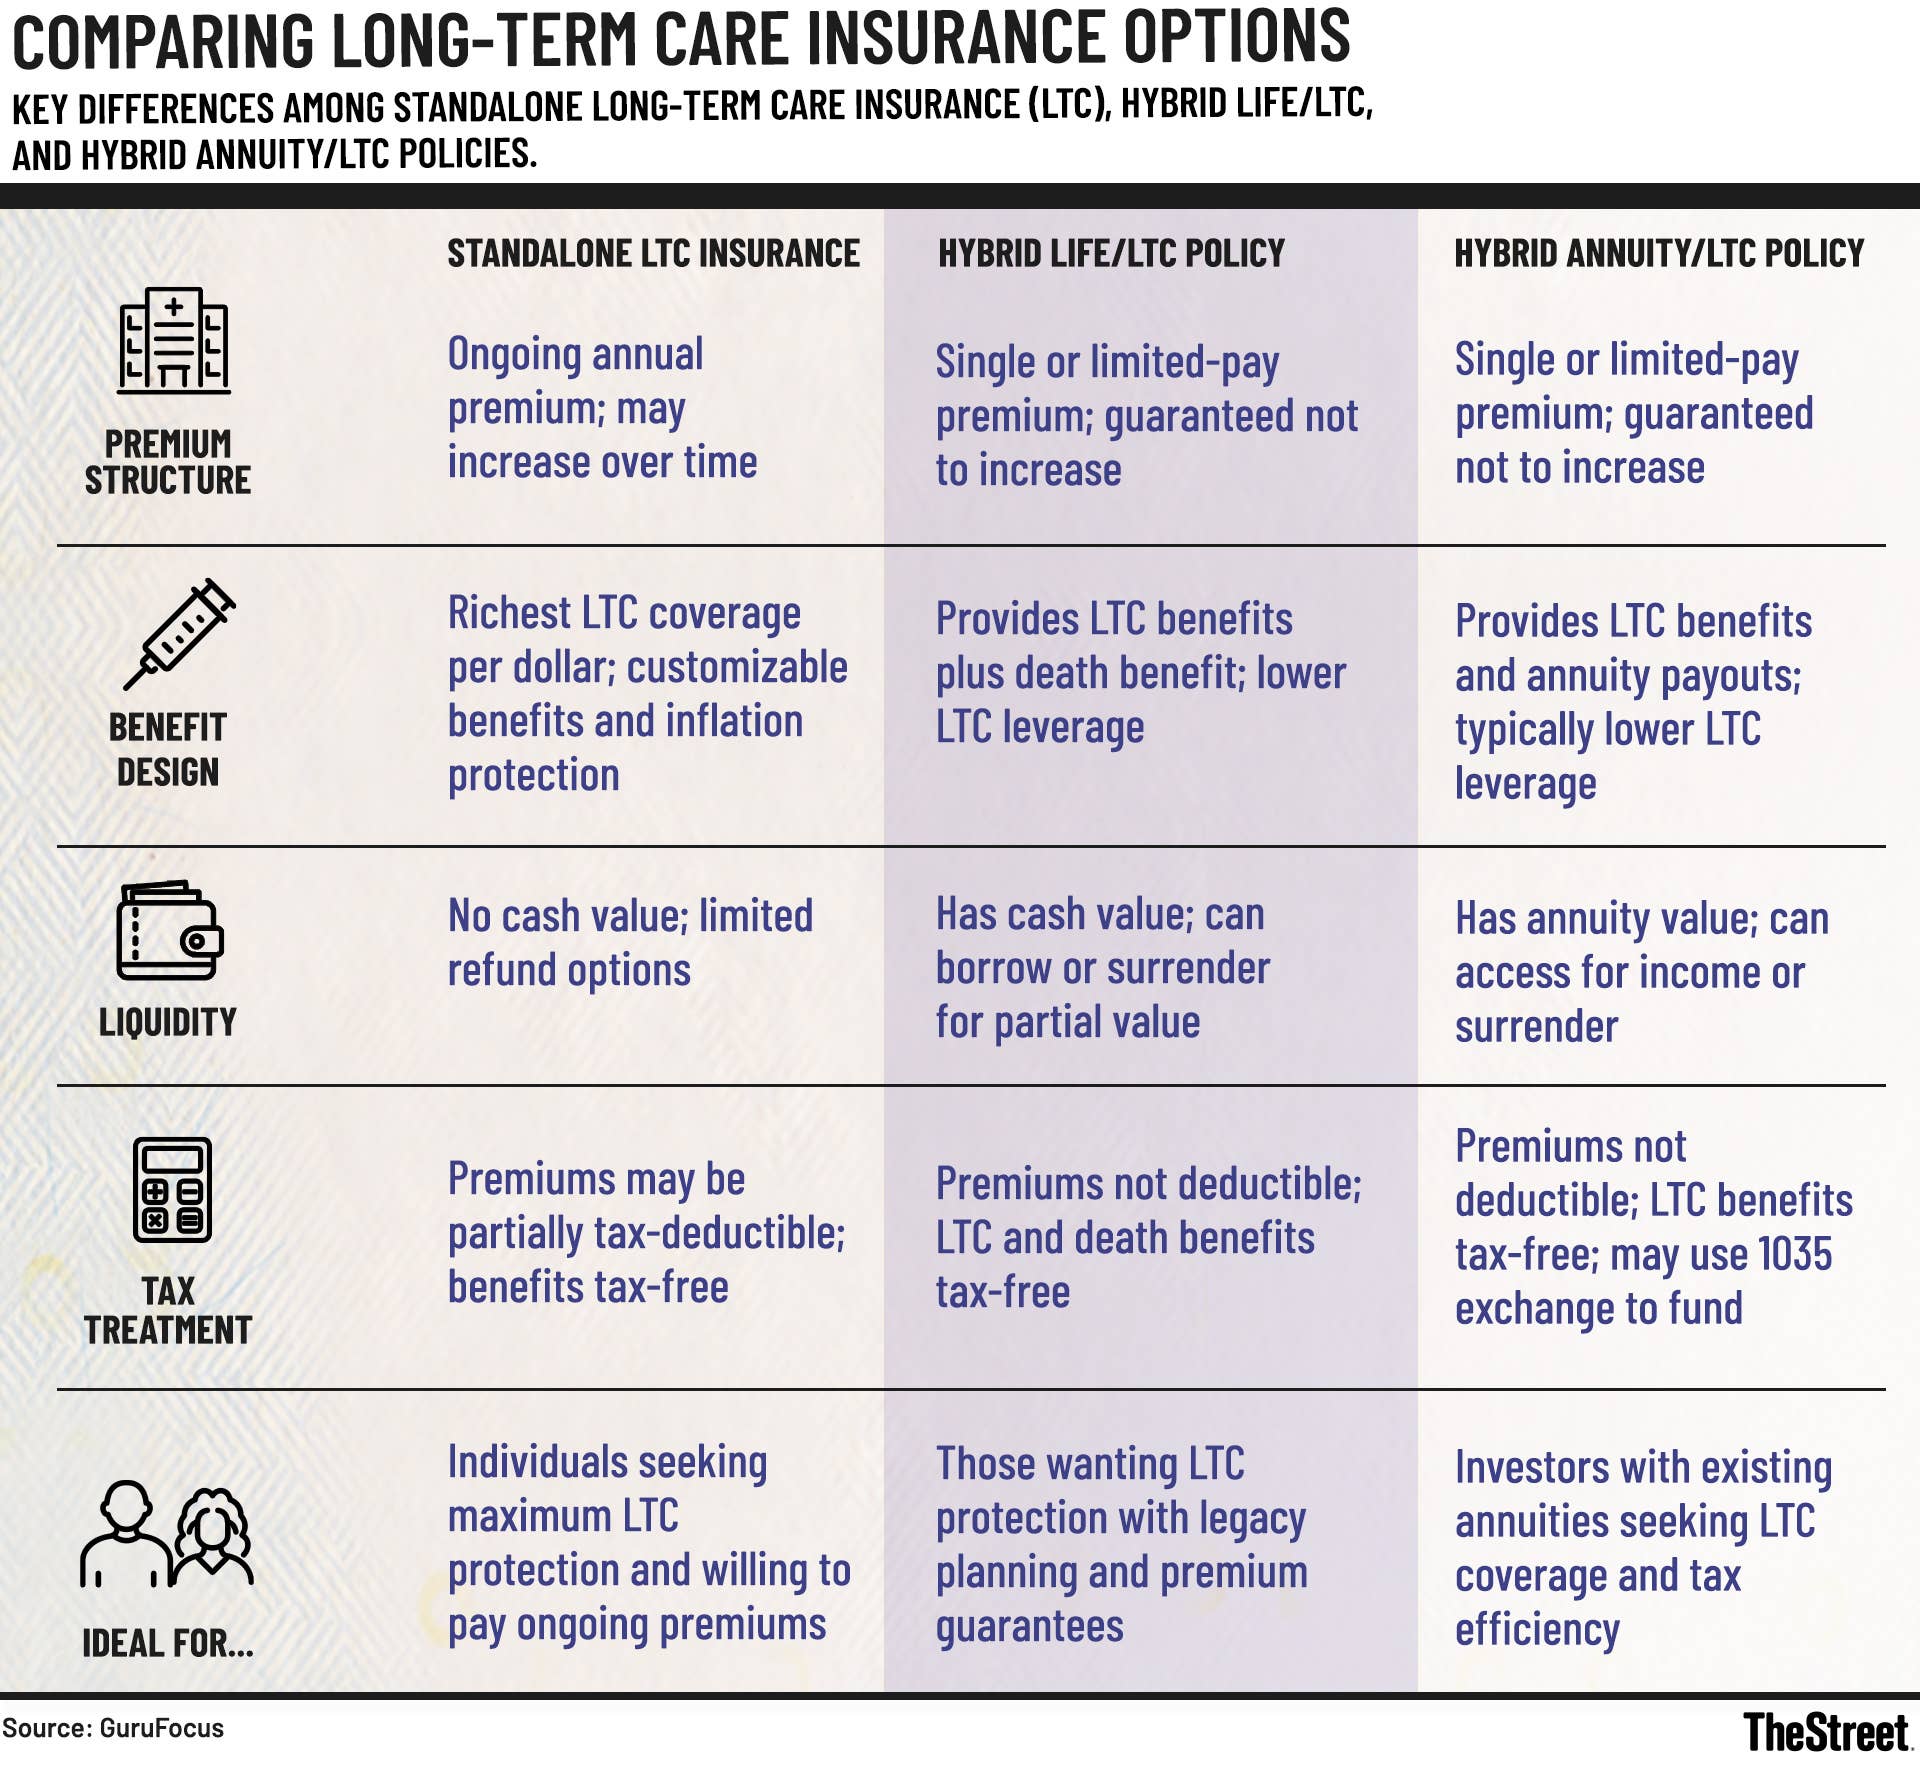
There are several types of long-term care insurance policies. They also may offer "hybrid" policies that integrate life insurance with long-term care insurance coverage, and some employers or associations provide group protection that offers more benefits for lower premiums.
Retirement Planning Ontario CAThe coverage is based on the month-to-month (or everyday) benefit total up to pay for care. When investigating, be sure to look up the average cost of care in your area and account for inflation to determine the quantity of care you will need. The expense of care in 2026 will likely be lower than the expense of care in 2042, so inflation security and comparable riders are rewarding financial investments.
Expected 2026 LTC Cost Trends
After the policy is provided, the carrier may raise premiums or you may elect to pay lower premiums for a lower advantage. The insurance company will then review medical records and, if approved, repay you for long-lasting care up until your policy limitation is reached.
Many long-term care insurance coverage are tax-qualified, implying you may subtract premiums from your annual income tax return through the medical expense reduction. The amount you can deduct in 2026 as a medical expenditure depends upon your age. $450 $850 $1,690 $4,510 $5,640 These rates may change each year, so contact a trusted financial consultant before filing your medical cost deductions.
That allows you to utilize a survivor benefit while you're still conscious pay for long-lasting care if it's required. If not, then your enjoyed ones will get the complete death benefit. The disadvantage is that hybrid policies typically are more pricey than traditional life insurance policies, and they do not get approved for the tax benefits that long-term care insurance coverage policies do.
If your health condition increases your long-lasting care insurance coverage premiums, however, then it might be affordable to acquire a hybrid policy as opposed to an individual long-lasting care insurance plan. If you identify you require a long-term care insurance coverage policy, then ensure to do your research study before purchasing. Keep the following pointers in mind while you're shopping: If you already have an insurance coverage representative, then a trusted adviser can assist you discover the right policy for the best value.
A hybrid insurance option may make sense if you're older or not in the very best health. The price of long-term care likely will increase by the time you require it, so keep that in mind when picking the advantage amount you need covered. Your employer (or ex-employer, if you're retired) might offer group coverage that is less costly than a private policy.
How Seniors Should Benefit From Accident Insurance
See if you're eligible before acquiring a policy. To get the most out of your long-lasting care insurance coverage policy, make certain your favored policy is tax-qualified so you can deduct premiums. To learn more about long-lasting care insurance, have a look at our handy guides.
The function of this product is solicitation of specific insurance. An insurance coverage agent may contact you. Policy forms ICC18-LTCD PLCY (0218 ), LTCD PLCY (0218 ), LTCD-U PLCY (0218 ), ICC14-LTC6, LTC6, LTC6-U, and any state-specific, are issued by New York Life Insurance Coverage Business, New York, NY. Policy types ICC20-AF-MP, ICC20-AF-SP, AF-MP, AF-SP, 316-60P & 316-284R, 316-150P & 316-283R and any state-specifics, are released by New york city Life Insurance and Annuity Corporation, Newark, DE, an entirely owned subsidiary of New York Life Insurance Coverage Company.
Financing approval is required to purchase protection and a medical examination might be required. The business books the right to increase premiums in the future. For expense and complete details of the protection, call your representative or the business. New York Life Insurance Company and New York City Life Insurance Coverage and Annuity Corporation have the sole financial duty for its own items.

Latest Posts
Securing Your Savings With Accident Coverage

Estimating Future LTC Costs

Comparing Long-Term Care Coverage Versus Medicare