All Categories
Featured
Comparing Care Policies Vs. Medicare Benefits
Table of Contents
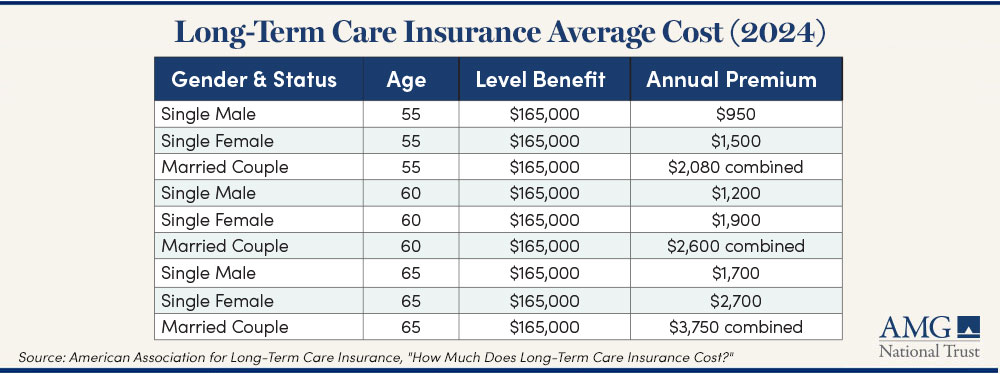
Data source: American Association for Long-Term Care Insurance (AALTCI) 2026 Rate Index evaluating top U.S. LTC underwriters (insurance provider) throughout choose age criteria (55, 60, 65) for single men/women along with married couples/partners. 2026 AALTCI Long-Term Care Insurance Rate IndexUpdated July 2026 COUPLE BOTH AGE 55: - According to the 2026 AALTCI Long-Term Care Insurance Price Index, the average annual premium for a 55-year-old couple (both) purchasing $165,000 in initial benefits is $5,010 (integrated expense for both).
SINGLE FEMALE AGE 60: - According to the 2026 AALTCI Long-Term Care Insurance Price Index, the typical annual premium for a 60-year-old female buying $165,000 in preliminary benefits is $4,450. In 2025, the anticipated expense reported was $4,550. For 2026, AALTCI reports that the spread between the most affordable and the greatest provider rates for the same profile varies by up to 29%.
Retirement Planning Irvine CAThe policy includes a 3% substance growth alternative - so that advantages increase by 3% yearly. The 2026 spread between the most affordable and the greatest provider rate for the very same profile varies by approximately 80%. The following are real long-term care insurance coverage expenses for an Illinois couple who are both AGE 60.
Generating Retirement Income With Permanent Policies
Rates will differ by state and will depend upon everyone's health at the time of application. Business 1: $4,591-per-yearCompany 2: $5,661-per-yearCompany 3: $6,440-per-yearCompany 4: $6,712-per-yearCompany 5: $7,173-per-yearIndividuals who Buy THE THE MAJORITY OF pricey long-term care insurance coverage policy will PAY 56.24% MORE each year for virtually identical coverage. This is why the Association recommends working with an independent long-term care insurance specialist who can compare policies from multiple insurer.

2026 prices are based on contrasts performed by the American Association for Long-Term Care Insurance (July 2026). The preliminary policy advantage equal $165,000 for a private with some health concerns.
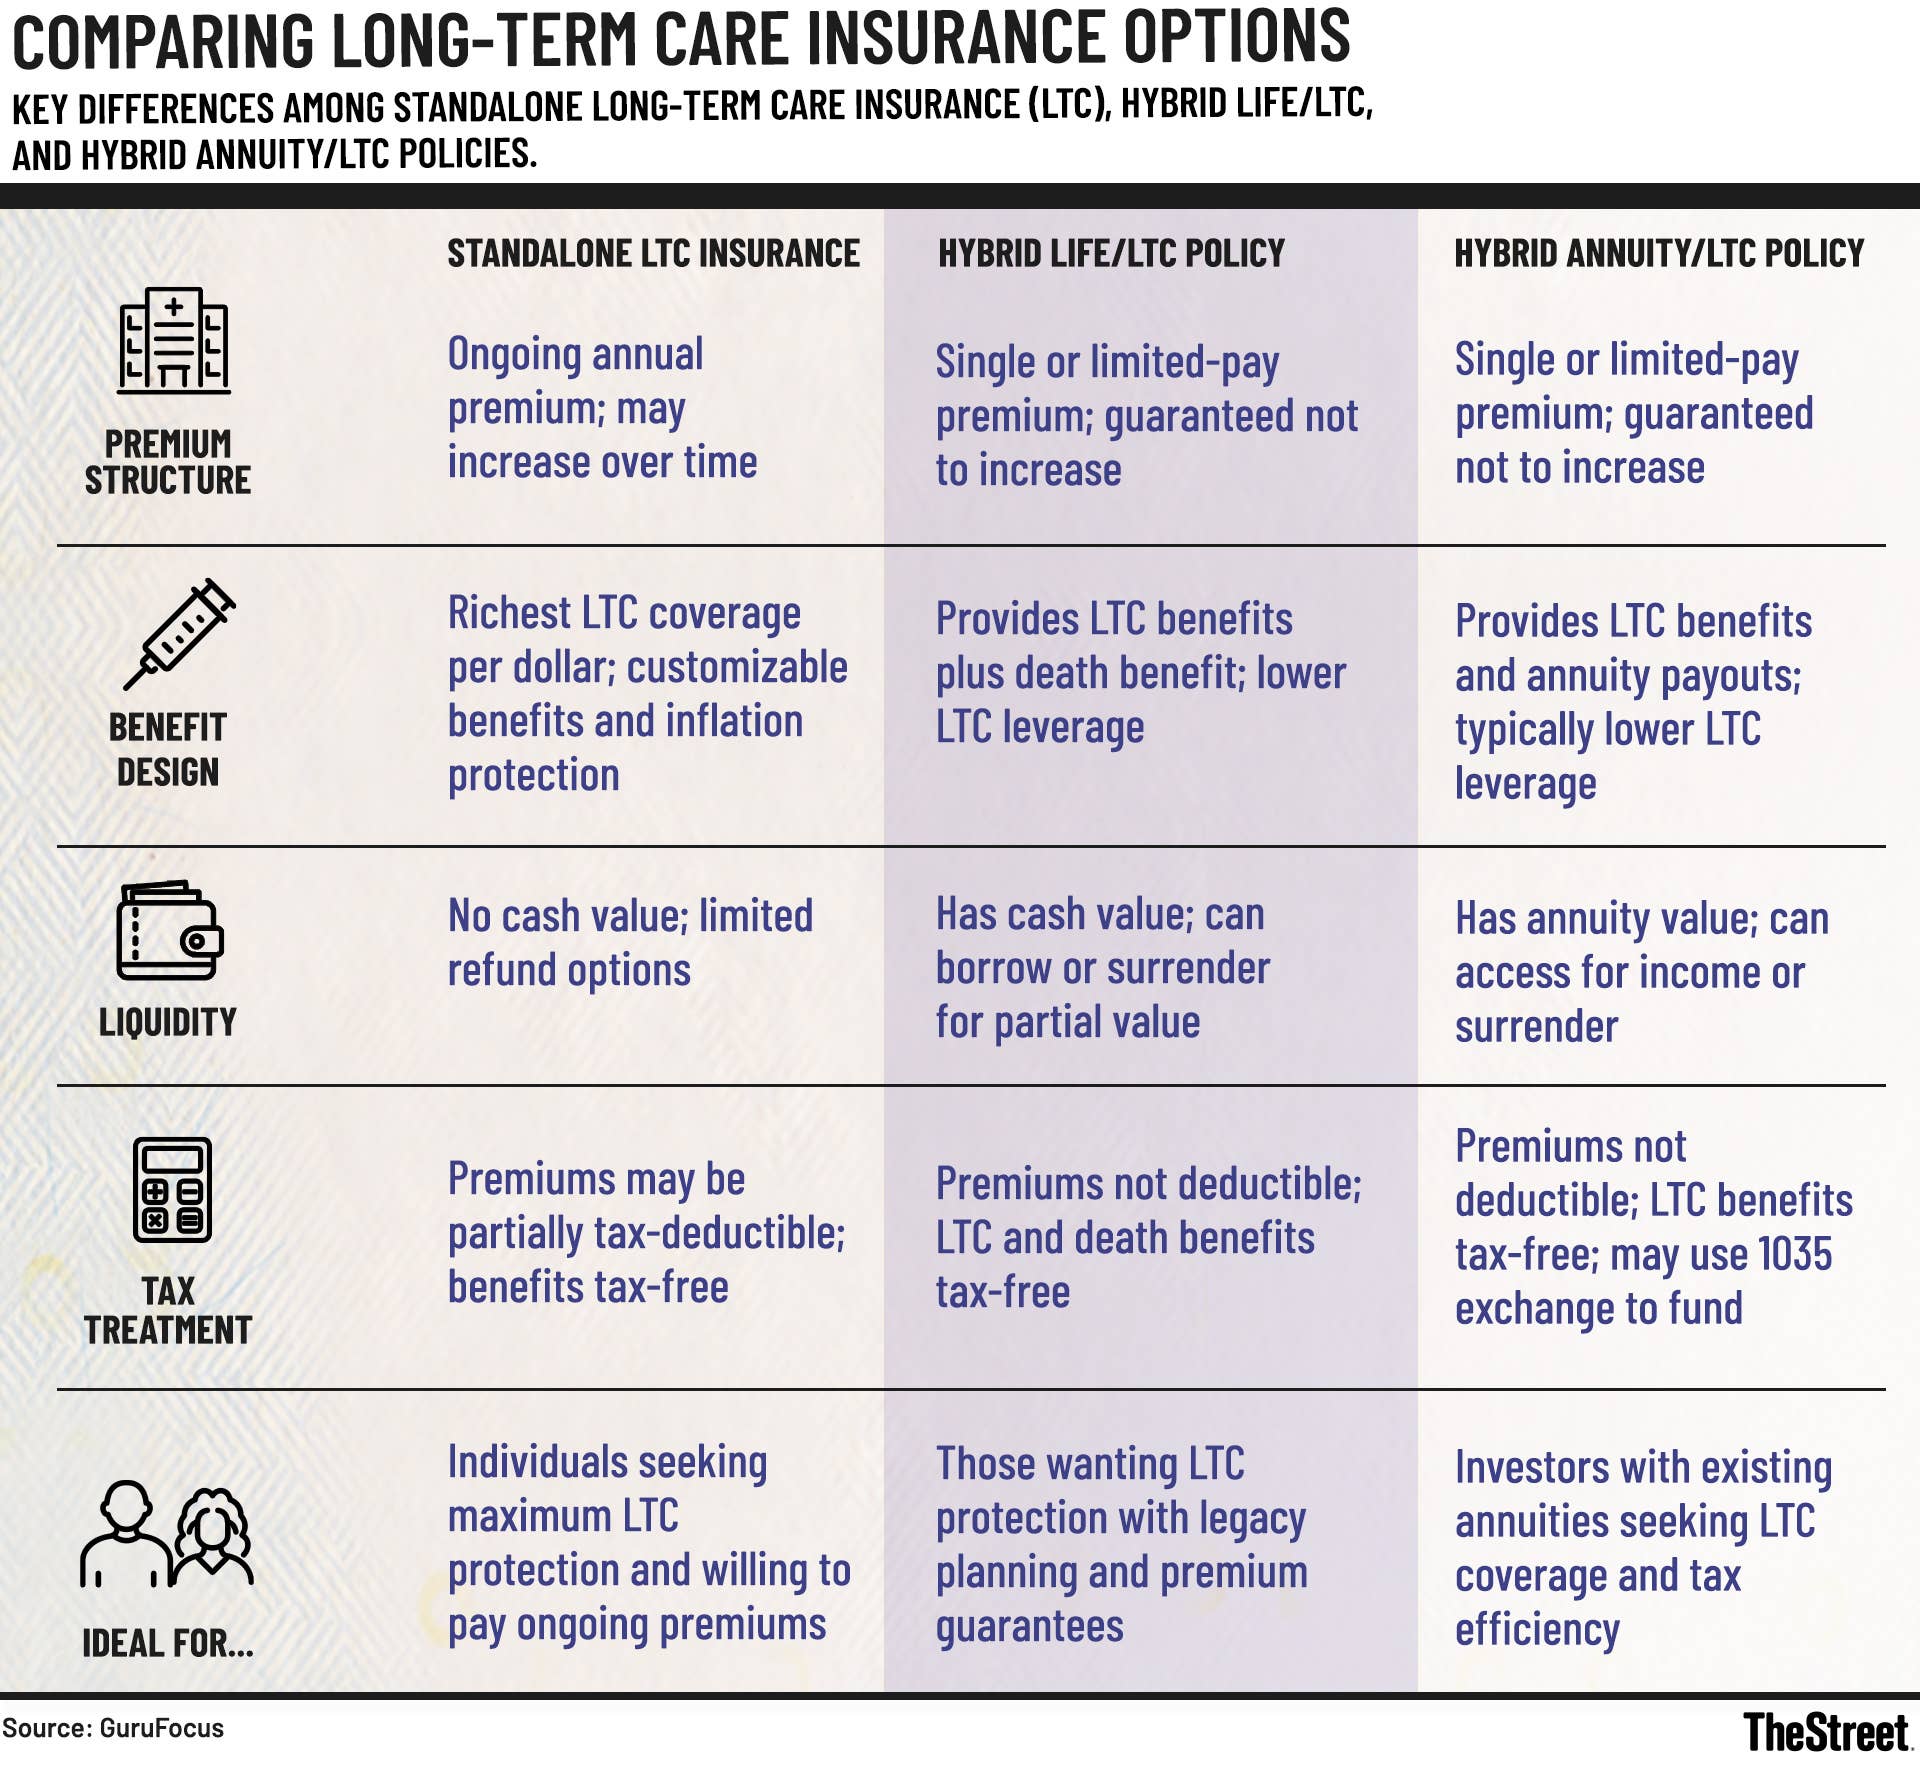
Today, it's wise to think about both standard as well as linked-benefit long-lasting care insurance. Many consumers being provided a linked-benefit LTC insurance policy incorrectly believe they cost about the very same as a traditional long-lasting care insurance policy.
They like the ability for beneficiaries to receive a death advantage if long-lasting care is not needed. Linked-benefit items today vary significantly and it is essentially difficult to offer an "apples-to-apples" contrast with conventional long-term care insurance coverage policies.
According to AALTCI, in 2026 a traditional LTC insurance plan that offers $180,000 of prospective LTC benefits can cost a guy who is age 55, about $1,050-a-year. Compare that to a connected advantage policy that provides a $180,000 pool of long-term care benefits in addition to a minimum survivor benefit of ($120,000).
How Senior Accident Insurance Protects Wealth
Policy price contrasts carried out July 2026 and subject to change. NO INFLATION GROWTH - Cost Revealed Equates To YEARLY PREMIUMS Single Male, Age 55 - Pool of LTC Benefits = $180,000 Cost: $1,050 Single Female, Age 55 - Swimming Pool of LTC Advantages = $180,000 Cost: $1,645 Company A: Expense Revealed Equates To YEARLY PREMIUM PAYMENTS Single Male, Age 55 - Swimming Pool of LTC Benefits = $180,000/ Minutes.
survivor benefit = $120,000 Expense: $3,265 Business B: Cost Revealed Equals YEARLY PREMIUM PAYMENTS Single Male, Age 55 - Pool of LTC Benefits = $240,000/ Minutes. survivor benefit = $120,000 Expense: $3,750 Single Female, Age 55 - Swimming Pool of LTC Advantages = $240,000/ Min. survivor benefit = $120,000 Cost: $3,555 Rates above include.
Determined: July 2026 Customers thinking about finding out more about connected advantage long-lasting care insurance plan that include a development option so that benefits increase gradually should call the Association to identify an experienced and independent LTC insurance specialist who provides policies from numerous insurance companies. Here are 10 crucial reasons according to the American Association for Long-Term Care Insurance coverage that it pays to work with an independent specialist when going shopping for long-term care insurance.

Latest Posts
Choosing the Best Annuity for Retirement
Essential Financial Planning for Future Needs
Elderly Accident Insurance Benefits and Value