All Categories
Featured
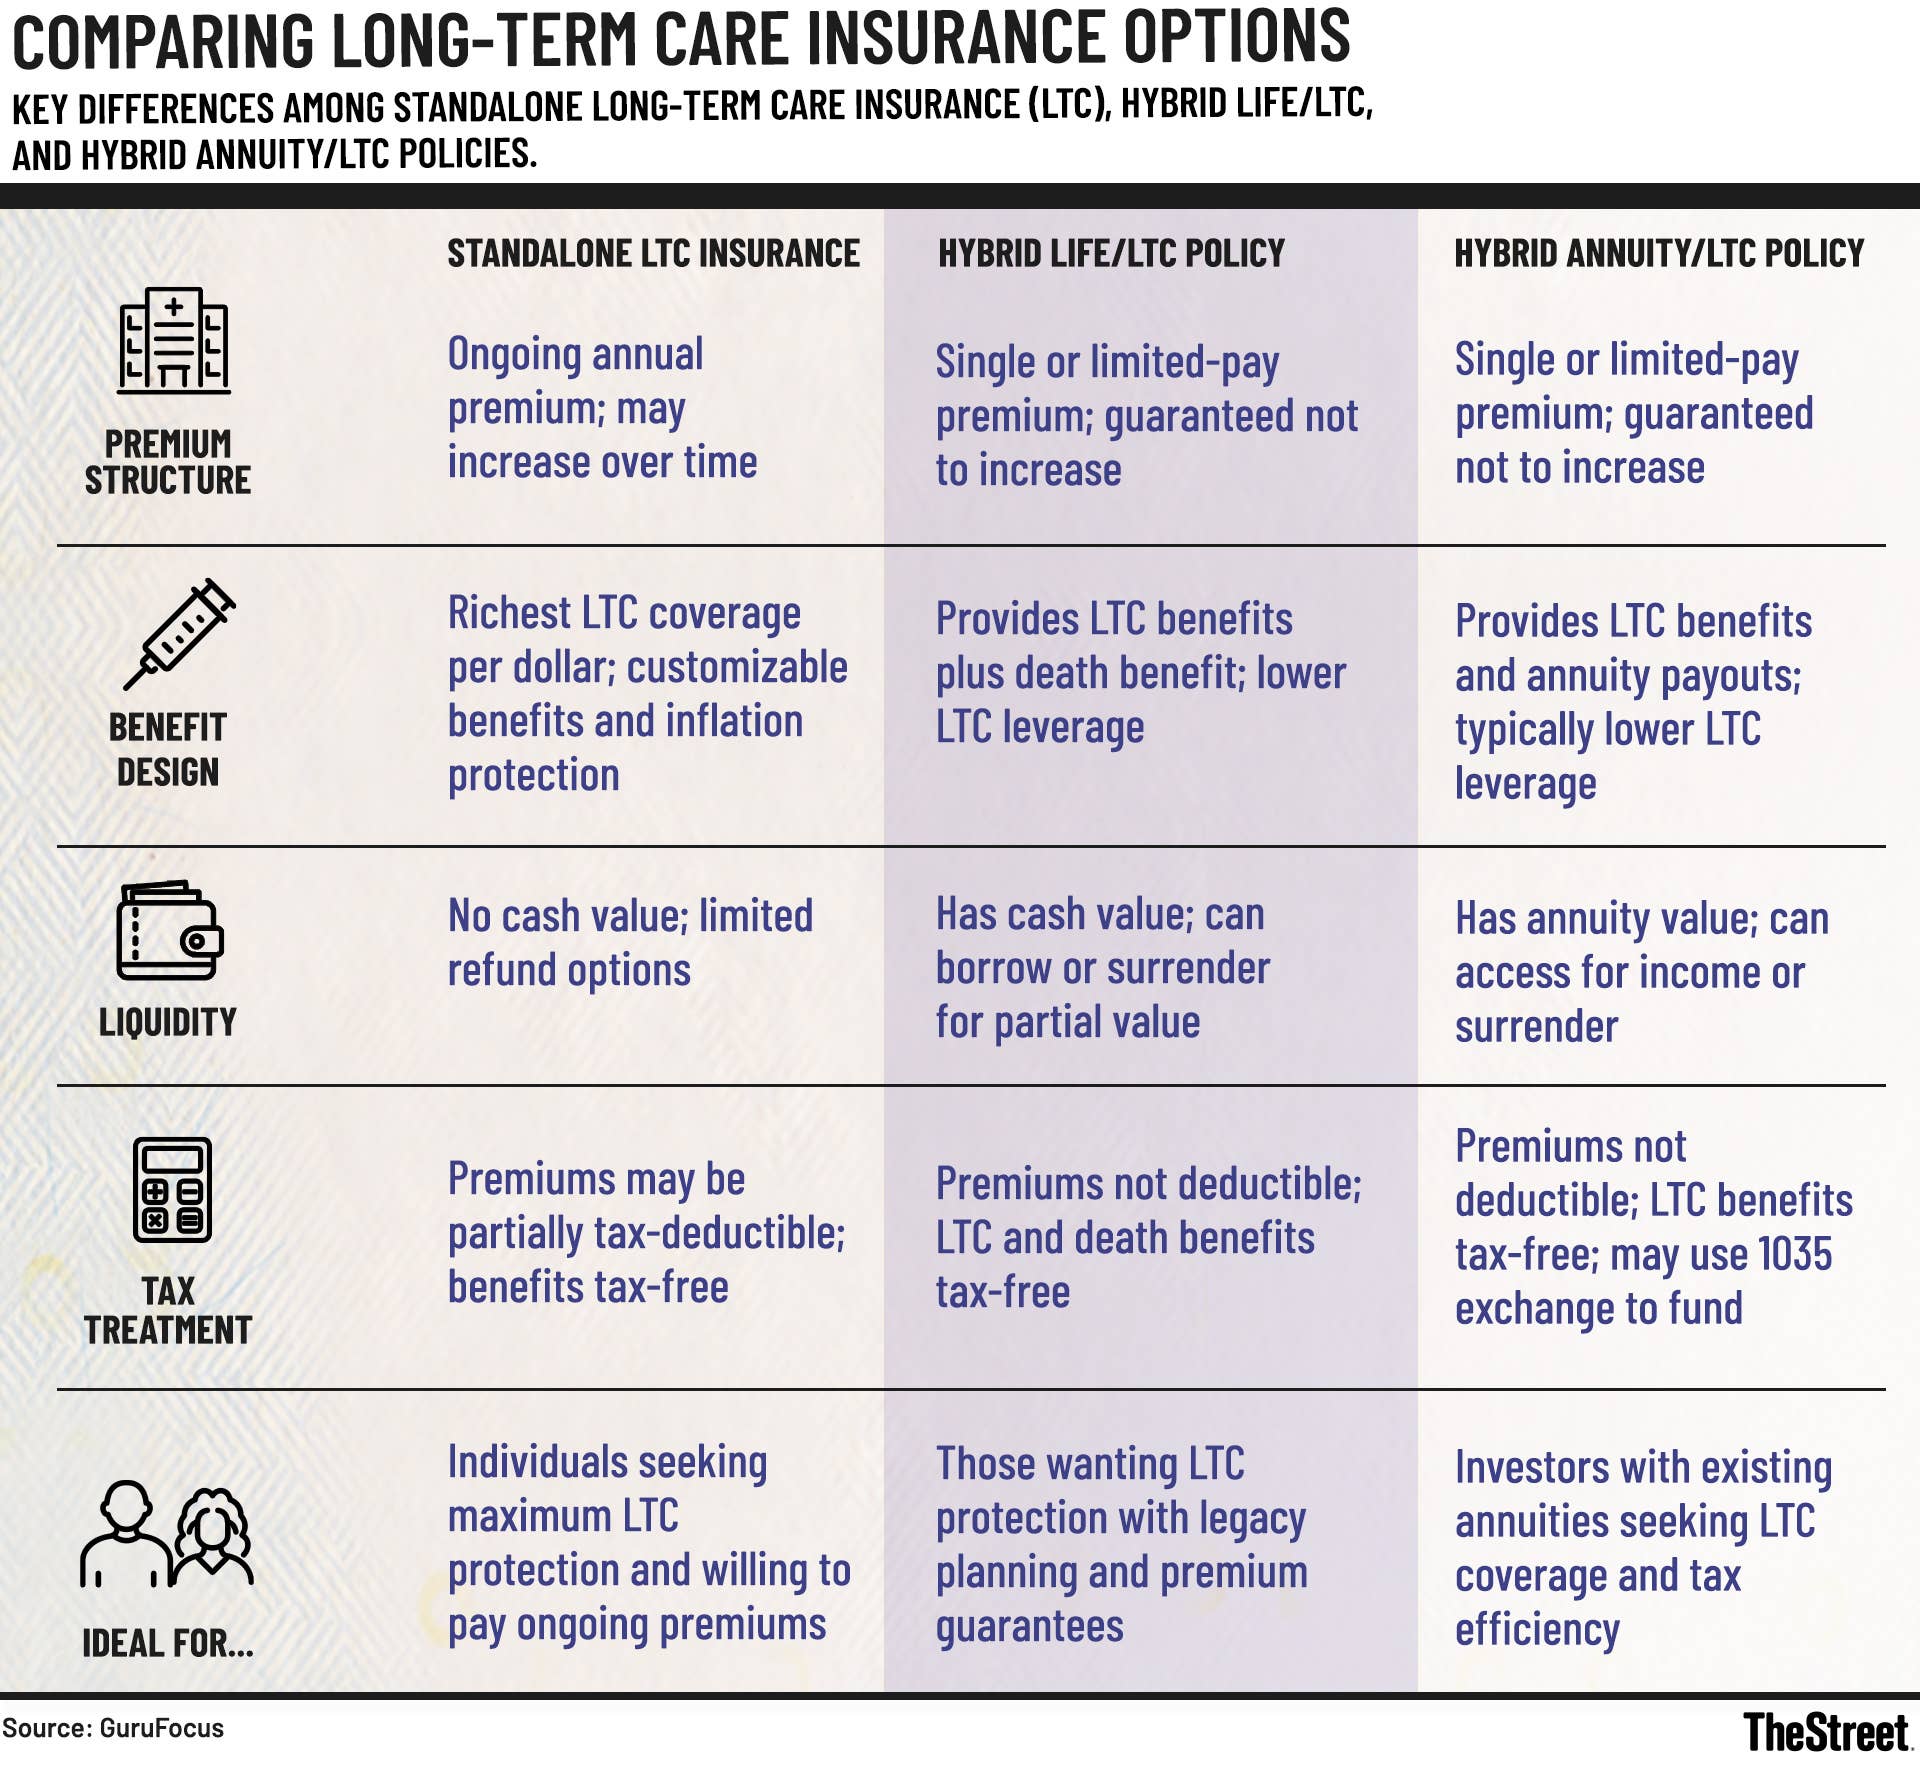
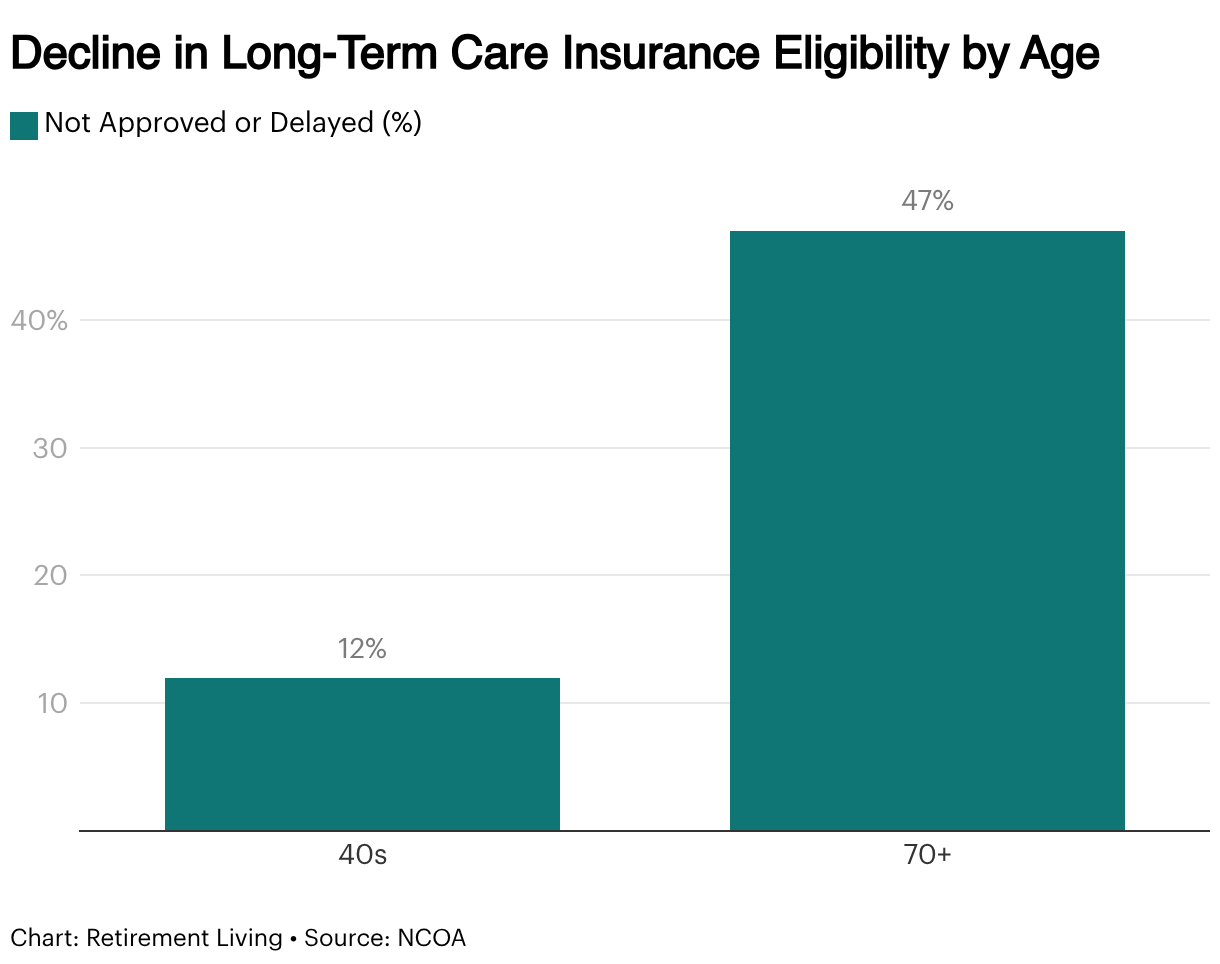
Essential Financial Planning for Future Needs
Table of Contents
Different insurers typically charge extremely different rates for comparable benefits Before signing anything, go into the business's monetary strength. You'll want a company that will still be around decades from now, particularly when it's time to sue. Every policy has information that can make a huge distinction. Search for: Removal periods (the waiting duration before benefits begin) Surefire renewability (so your protection can't be canceled if your health changes) Nonforfeiture alternatives (to maintain some value if you cancel the policy) Take the time to examine all terms, conditions, and exemptions.

The great print frequently covers stipulations about how and when your benefits are paid, any limits on protection, waiting durations before advantages start, and whether your premiums could increase gradually. These suggestions can assist you discover the long-lasting care insurance that matches you best When preparing for retirement, many people concentrate on conserving enough to change lost earnings.
Long-term care insurance helps cover those costs, securing your financial resources and supplying comfort in retirement., we understand that the expense of long-lasting care can be a major issue. That's why we provide versatile, personalized care options, so you just pay for the level of assistance your loved one genuinely needs, whether it's for a few hours, a week, or longer.
Retirement Income Planning Using Life Insurance
This assists you manage expenses while guaranteeing your liked one gets safe, trustworthy care. Here's a glimpse at how long-term care insurance modifications with age: $1,200$3,700 each year $2,075$6,600 per year $3,600$12,375 annually (higher threat) The finest time to purchase long-lasting care insurance is normally Long-lasting care insurance premiums are based upon your age and health at the time you apply.
Vaccines are a vital part of healthy aging and these guides can help you understand which one's matter most:.
Retirement Planning Irvine CAThe Health Insurance Marketplace Open Registration Period for strategy year 2026 begins on November 1, 2025, and runs up until January 15, 2026. The average premium after tax credits is forecasted to be $50 each month for the least expensive expense strategy in 2026 for qualified enrollees. This represents a $13 increase from 2025.
Severe Illness Coverage for Seniors
Premium Cost: Qualified enrollees continue to have robust access to low premium plans after applying advance payments of the exceptional tax credit. Comparable to 2025, typically, tax credits are predicted to cover 91% of the most affordable cost plan premium in 2026 for eligible enrollees. This compares to 85% in the 2020 protection year, which was the last protection year not affected by temporary COVID-19 pandemic policies.
While this represents a $13 boost from 2025, it remains $20 more economical than the month-to-month premium after tax credits in 2020. In 2026, almost 60% of eligible re-enrollees will have access to a strategy in their chosen health strategy category at or listed below $50 after tax credits. This compares to 83% of eligible enrollees in 2025 and 56% in 2020 with comparable gain access to.
The typical 2026 enrollee has between 6 and 7 QHP companies offered. In 2026, 95% of enrollees have access to 3 or more QHP providers, compared to 96% in 2025 and 68% in 2020. In addition, less than 1% of 2026 enrollees have just one readily available QHP provider, which is the lowest percentage in history.
In 2026, this will make HSA-eligible plans offered to every customer in every county throughout the states that use This expands access to HSA-eligible strategies to a minimum of 1.6 million extra consumers. ###.
Vaccines are a vital part of healthy aging and these guides can assist you comprehend which one's matter most:.
Severe Illness Insurance for Seniors
The Medical Insurance Marketplace Open Enrollment Duration for strategy year 2026 begins on November 1, 2025, and runs till January 15, 2026. The typical premium after tax credits is predicted to be $50 monthly for the most affordable expense strategy in 2026 for eligible enrollees. This represents a $13 boost from 2025.
Premium Price: Eligible enrollees continue to have robust access to low premium plans after applying advance payments of the exceptional tax credit. Comparable to 2025, usually, tax credits are projected to cover 91% of the most affordable expense plan premium in 2026 for eligible enrollees. This compares to 85% in the 2020 coverage year, which was the last coverage year not impacted by momentary COVID-19 pandemic policies.
While this represents a $13 increase from 2025, it remains $20 less costly than the month-to-month premium after tax credits in 2020. In 2026, almost 60% of eligible re-enrollees will have access to a strategy in their picked health insurance classification at or listed below $50 after tax credits. This compares to 83% of qualified enrollees in 2025 and 56% in 2020 with equivalent access.
The average 2026 enrollee has between 6 and 7 QHP companies offered. In 2026, 95% of enrollees have access to three or more QHP providers, compared to 96% in 2025 and 68% in 2020. In addition, less than 1% of 2026 enrollees have just one readily available QHP company, which is the most affordable percentage in history.
Critical Illness Coverage for Seniors
In 2026, this will make HSA-eligible plans offered to every consumer in every county throughout the states that utilize This broadens access to HSA-eligible strategies to a minimum of 1.6 million additional customers. ###.

Latest Posts
Choosing the Best Annuity for Retirement
Essential Financial Planning for Future Needs
Elderly Accident Insurance Benefits and Value